Rising US credit card debt tells only part of the story of household financial stress. Gies Business finance professor Avantika Pal says consumers are increasingly supplementing traditional borrowing with alternative credit products such as online installment loans and short-term cash advances.
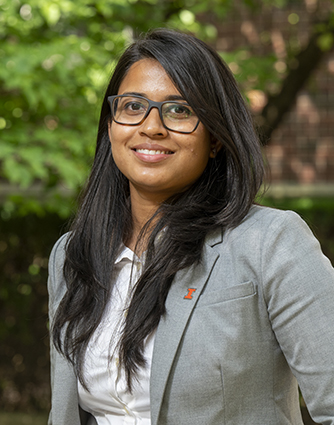
The Federal Reserve Bank’s latest Quarterly Report on Household Debt and Credit noted that American credit card debt rose to $1.26 trillion, just shy of the peak of $1.28 trillion from the fourth quarter of 2025. But according to Avantika Pal, an assistant professor of finance at Gies College of Business, those headline numbers also raise a broader question: how households are supplementing traditional credit with nontraditional forms of borrowing.
Pal’s primary research focuses on household finance. She analyzes credit bureau data and studies all forms of consumer debt, including what leads households to financial distress and how different government regulations and policies could alleviate some of that distress.
Her latest study analyzes a one percent random sample of those who report to Experian. She finds that the increase in traditional forms of credit such as credit cards and mortgages is actually not unusually sharp. But some alternative forms of credit, such as online installment loans, may be less visible in conventional measures of household debt. Combined with higher costs due to inflation, she says these products are worth watching.
“This alternative debt is complementary to credit card debt, which acts as a liquidity bridge between paychecks,” Pal explains. “When borrowers are close to their credit card limits, installment loans can offer another source of short-term liquidity and smaller scheduled payments. That flexibility can be useful, but it may also make it easier for financially stretched households to take on additional debt.”
Pal says that the online installment loans are easier and quicker to access than many traditional forms of credit, sometimes with more limited underwriting.
“What stands out is how accessible some of these products have become,” Pal said. “The problem is that some of these newer products can fall into regulatory gaps or be governed differently from traditional bank credit. That makes it important to keep evaluating whether existing consumer protections adequately cover these forms of borrowing.”
Delinquency rates also capture only one dimension of household financial stress, Pal says. Although 60 percent of Americans don’t pay off their credit card balances each month, they remain current if they make at least the minimum payment.
“Credit card debt is a revolving form of credit,” Pal said. “Paying the minimum keeps an account current, but the balance can persist, and interest costs accumulate. For households consistently using a large share of their available credit, that can reduce financial flexibility over time.”
To pay off some of the debt on maxed-out credit cards, households are turning to more traditional sources like home equity lines of credit (HELOC), which leverage the value of your home and still carry high interest rates. As mentioned, though, more and more Americans are turning to alternative credit options, which can be approved online without visiting a bank or going through a credit check and provide relatively quick access to cash. The important question, Pal says, is how these different forms of borrowing interact when households are already financially constrained.
Nowadays, a growing class of fintechs provides short-term cash advances against future income without charging explicit interest. Instead, borrowers can voluntarily leave a tip, with repayment typically debited on the next payday. Although these products are marketed as “interest-free,” the tips borrowers choose to pay can imply borrowing costs comparable to those of traditional high-cost credit products. They can help bridge a temporary cash shortfall, but repeated use can become expensive for households with limited financial buffers.
Pal sees a broader lesson in earlier periods of rapidly expanding credit: when borrowing becomes easier, the key question is whether underwriting, disclosure, and consumer understanding keep pace.
Online installment loans can provide consumers with useful liquidity and lower scheduled payments, but smaller periodic payments can also make the total cost and cumulative debt burden less salient to borrowers.
Alternative credit trends also matter for the housing market
Similar questions about nonbank finance arise in mortgage servicing.
Pal is a co-author of a study titled “The Rise of Non-Banks in Servicing Household Debt,” which takes a look at the trend of banks transferring mortgage servicing to non-bank financial institutions. Nonbanks operate under different funding, liquidity, and regulatory structures than traditional depository banks.
“They have different funding and liquidity structures, and those differences can affect how loans are serviced, particularly when borrowers are in distress,” Pal said. “Our research finds worse outcomes following some transfers to nonbank servicers, including higher foreclosure rates. Understanding which features of the servicing model drive those outcomes is an important question.”
Financial literacy and consumer protection may both matter
Pal says policy should continue to pay attention to credit products that fall outside traditional regulatory frameworks or are reported differently from conventional bank credit. Potential responses could include clearer disclosure of borrowing costs, more consistent credit-bureau reporting and periodic reassessment of whether existing consumer protections cover newer lending models.
Pal also sees financial education—especially around compounding, minimum payments and the total cost of borrowing—as a useful complement to consumer protections.
“Even financially sophisticated people can find credit products difficult to compare,” Pal said. “Financial literacy can help consumers understand the full cost of debt—for example, how interest accumulates when only the minimum payment is made. Better information does not replace regulation, but it can help households make more informed choices.”
For now, Pal says the growth of non-traditional credit deserves closer measurement and monitoring.
“The rise in alternative financing is important to track,” Pal said. “These products can provide useful liquidity, but we also need to understand when they relieve short-term constraints and when they add to longer-term financial stress.”